Japan qualified invoice: the required entries
The six entries a Japanese qualified invoice must carry, the registration number, rounding by tax rate, simplified invoices and what changed on 1 October 2026.
At a glance
The six entries a qualified invoice must carry
Under the qualified invoice system that began on 1 October 2023, a buyer generally needs to keep the qualified invoice the seller issued in order to claim an input consumption-tax credit. A missing entry therefore costs your counterparty, not you — which is why the document comes back before the payment does.
The layout itself is free. An invoice, a delivery note or a receipt all qualify as long as the six entries below are present; conversely, a well-formatted document that omits the registration number or the applicable rate does not meet the requirement.
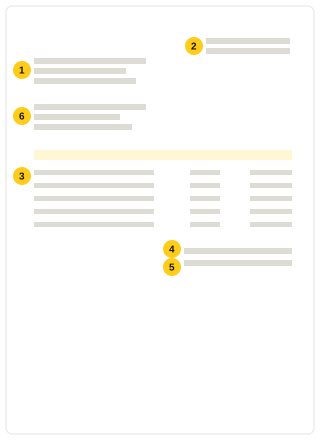
- The name of the registered invoice issuer and their registration number.
- The date the taxable supply was made.
- What was supplied, including a marking where the reduced rate applies.
- The amounts totalled separately for each tax rate, and the rate applied.
- The consumption tax amount for each tax rate.
- The name of the business receiving the document.
The registration number is "T" plus 13 digits
A registration number is the letter T followed by thirteen digits. For a company the digits are its corporate number; sole proprietors and unincorporated associations are assigned a separate thirteen-digit number. A business that is not registered cannot issue a qualified invoice at all.
You can confirm a counterparty's registration number on the National Tax Agency's published register. For an ongoing relationship it is worth re-checking occasionally rather than only once, since a registration can be cancelled.
Splitting by rate, and rounding once
The standard rate is 10% and the reduced rate is 8%. The reduced rate covers food and drink other than alcohol and eating out, and newspapers supplied under a subscription; items at the reduced rate must be marked as such, which a symbol explained in a footnote satisfies.
Rounding happens once per invoice per tax rate. Calculating tax line by line and adding the results is not accepted, and that is exactly what an older spreadsheet format tends to do — the requirement is easy to miss when a familiar layout is reused.
Buying from an unregistered business, and the transitional relief
A taxable purchase from a supplier who is not a registered invoice issuer does not, as a rule, qualify for an input tax credit. Transitional relief softens that: 80% of the equivalent input tax could be credited from 1 October 2023 to 30 September 2026. The 2026 (Reiwa 8) tax reform changed the steps after that. According to the National Tax Agency’s page on the reform, read on 5 October 2026, the credit is 70% from 1 October 2026 to 30 September 2028, 50% from 1 October 2028 to 30 September 2030 and 30% from 1 October 2030 to 30 September 2031, and nothing from 1 October 2031.
Claiming the relief requires keeping a document carrying the same entries as the earlier classified invoice, and noting in the books that the relief is being applied. For tax periods beginning on or after 1 October 2026, it does not apply to the part of a year’s purchases from any one unregistered supplier above JPY 100 million including tax (JPY 1 billion before the reform). Around the date the percentage changes, which period the purchase falls in decides which rate applies.
What changed on 1 October 2026
The 2026 (Reiwa 8) tax reform revised the transitional rules of the invoice system. According to the National Tax Agency’s reform page and its 20% special rule page, read on 6 October 2026, the changes take effect around 1 October 2026 and touch both buyer and seller. The percentages above are the buyer’s side.
- The share of input tax creditable on purchases from unregistered suppliers, such as tax-exempt businesses, fell from 80% to 70%. It becomes 50% from October 2028, 30% from October 2030 and nothing from October 2031.
- The relief stops at JPY 100 million a year of purchases from any one unregistered supplier (JPY 1 billion before), for tax periods beginning on or after 1 October 2026.
- The 20% special rule ends with the tax period that includes 30 September 2026: the 2026 year for a sole proprietor, the year to March 2027 for a company with a March year end.
- A new 30% rule for sole proprietors can be used in the 2027 and 2028 tax years.
The end of the 20% special rule, and the 30% rule for sole proprietors
The 20% special rule let a business that was tax-exempt and became a taxable business by registering as a qualified invoice issuer set the tax payable at 20% of the tax on its sales. It applies to tax periods that include a day from 1 October 2023 to 30 September 2026.
The 30% rule that follows is for sole proprietors only. A sole proprietor who became taxable by registering as a qualified invoice issuer can set the tax payable at 30% of the tax on sales in the 2027 and 2028 returns. The main conditions are being a sole proprietor, taxable sales of JPY 10 million or less in the base period (two years before the year, so 2025 for 2027), and being registered as a qualified invoice issuer. Companies are not covered.
A bridge to the simplified tax system is also provided: after a year under the 20% or 30% rule, the election form for the next tax period can be filed by that period’s filing deadline instead of the day before it starts. If that next period ends on or before 30 September 2026, the deadline is its last day.
These rules change how the tax payable is calculated, not what an invoice must show or the need for a registration number.
When a simplified invoice is allowed
Businesses that sell to the general public — retail, restaurants, photography, travel, taxis, parking and similar — may issue a simplified qualified invoice. It does not need the recipient's name, and it may carry either the applicable rate or the tax amount per rate rather than both.
The simplified form is allowed because of the nature of the business, not because a shorter document would be convenient. Check the National Tax Agency guidance to confirm whether your business is in scope.
Check before sending
In QuoteBill you set the document country and tax rate before reviewing the preview. The Japanese template supplies the structure and the field labels; the registration number and the description of the supply are yours to enter. Check the following against the finished PDF before sending.
0/6
Sample contracts, forms and tools
Sources
536 Free Invoice, Quote & Receipt Templates
Free invoice generator
Download the invoice as Excel or Word with working formulas (free for QuoteBill members), or edit it online with your logo and tax settings and save a PDF.
Free quotation generator
Download the quotation as Excel or Word with the formulas working (free for QuoteBill members), or edit it online and turn an accepted quote into an invoice.
Consultant invoice template
Create a consulting invoice for hourly or project work, research and report delivery. Add payment terms, review the total, then save a PDF or download Word.